How to Understand Define Good Faith Estimate in 2024

When a lender hands you a three-page document labeled "Loan Estimate" or a contractor provides a "preliminary cost breakdown," you’re encountering a define good faith estimate—a legally binding promise that the numbers you’re seeing are accurate to the best of their ability. This isn’t just bureaucratic jargon; it’s the cornerstone of trust in transactions worth billions annually, from mortgages to medical billing. The phrase itself carries weight because it forces accountability: if the final cost deviates by more than a few percentage points, you have recourse. Yet most people skim these estimates, unaware that their rights hinge on this single concept.
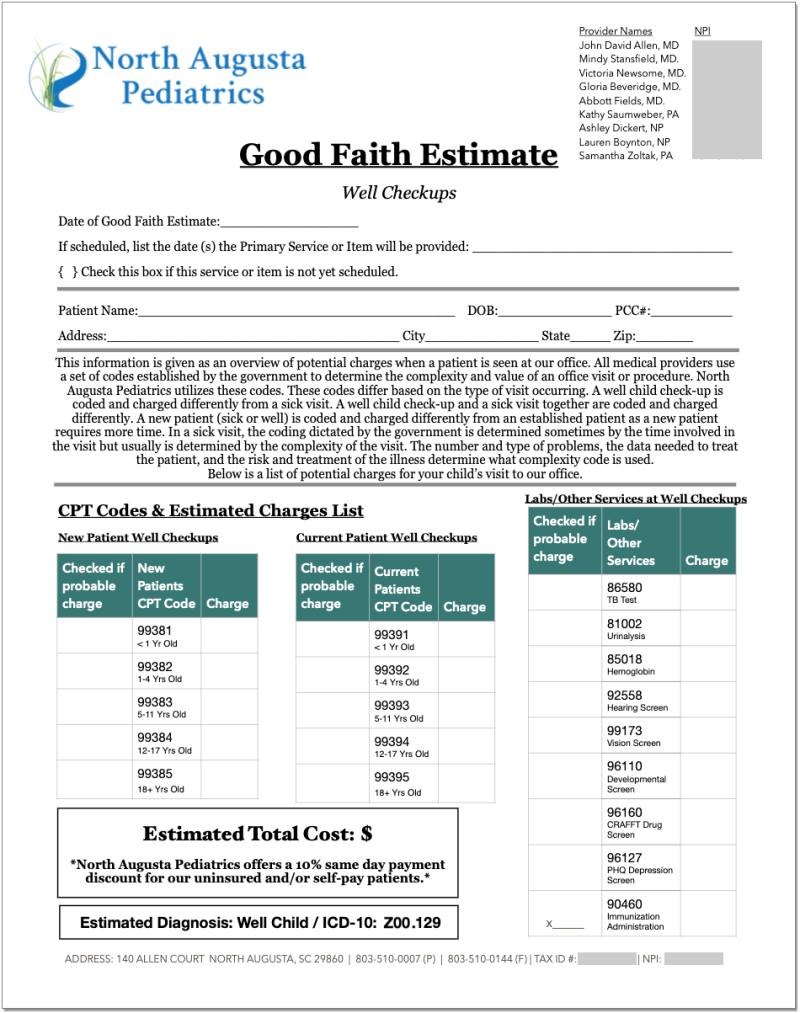
The define good faith estimate isn’t a fixed term in every industry, but its principles are universal. In healthcare, it’s the "expected out-of-pocket costs" form hospitals must provide before treatment. In construction, it’s the "bid estimate" that contractors swear by law to honor within tolerances. What ties them together is the legal expectation that the provider has made a reasonable effort to calculate costs fairly—and that you, as the consumer, can challenge discrepancies. The stakes are higher than ever, as regulatory bodies now treat deviations as potential violations, not just "honest mistakes."
Misunderstandings here cost consumers millions yearly. A 2023 CFPB report found that 40% of mortgage borrowers didn’t realize their good faith estimate could be adjusted if market rates shifted—leading to last-minute surprises. Meanwhile, in medical billing, patients often assume a $500 "estimate" means they’ll pay $500, only to face $2,000 charges. The define good faith estimate isn’t just about numbers; it’s about aligning expectations with reality before money changes hands.
The Complete Overview of Define Good Faith Estimate
At its core, define good faith estimate refers to a preliminary projection of costs, fees, or timelines provided by a service provider under the assumption that they’ve used reasonable methods to calculate it. The term gained prominence in U.S. consumer finance law after the Real Estate Settlement Procedures Act (RESPA) of 1974, which mandated that lenders disclose mortgage terms upfront. Over time, the concept expanded to healthcare (Affordable Care Act), construction (FTC guidelines), and even software licensing (California’s "as advertised" laws). Today, it’s less about a single document and more about a cultural shift: the idea that transparency isn’t optional, but a precondition for any transaction.What distinguishes a good faith estimate from a casual quote? Three key elements: 1) Reasonable basis—the provider must use verifiable data (e.g., historical pricing, vendor contracts); 2) Good-faith effort—they can’t lowball intentionally; and 3) Tolerance for error—small variances (typically ≤10%) are acceptable, but large ones may trigger penalties. Courts have ruled that even if a provider believes their estimate is accurate, they must demonstrate they didn’t ignore red flags (e.g., a contractor using outdated material costs). This legal standard has evolved alongside technology, where algorithms now generate define good faith estimates in seconds—but human oversight remains critical to prevent bias or oversights.
Historical Background and Evolution
The define good faith estimate traces back to 19th-century English common law, where courts required merchants to provide "fair and reasonable" pricing to avoid fraud claims. In the U.S., the concept crystallized during the Great Depression, when President Roosevelt’s Truth in Lending Act (1968) forced lenders to disclose interest rates transparently. The real turning point came with RESPA, which created the Good Faith Estimate (GFE) form—a standardized two-page document for mortgages. This was revolutionary: before RESPA, lenders could hide fees in fine print; after, borrowers could compare apples-to-apples.The 2010 Dodd-Frank Act overhauled the GFE into the Loan Estimate, expanding protections to include third-party service fees and closing disclosure timelines. Meanwhile, healthcare’s define good faith estimate emerged from the Affordable Care Act (2010), requiring providers to furnish cost estimates for uninsured patients within 300 hours of a scheduled service. These legal milestones reflect a broader societal demand for accountability—one that’s now extending to gig economy platforms (e.g., Uber’s fare estimates) and even AI-generated pricing models. The evolution isn’t just regulatory; it’s a response to consumer empowerment movements that treat estimates as contracts, not suggestions.
Core Mechanisms: How It Works
The mechanics of a good faith estimate vary by industry, but the framework is consistent. In lending, the Loan Estimate must include:Table of Contents
- The Complete Overview of Define Good Faith Estimate
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can a lender change my mortgage Loan Estimate after I’ve accepted it?
- Q: What happens if a contractor’s final bill exceeds their good faith estimate by 20%?
- Q: Are verbal good faith estimates legally binding?
- Q: How do I know if a healthcare provider’s cost estimate is accurate?
- Q: What should I do if a good faith estimate is clearly wrong?
- Q: Do good faith estimates apply to online purchases or subscriptions?
- Q: Can a good faith estimate be used against me in court?
The lender has three business days to deliver this after application, and any changes (e.g., credit score adjustments) must be justified. In healthcare, the define good faith estimate for a procedure like an MRI might list:
Providers must update these if circumstances change (e.g., unexpected complications). The critical threshold is the "tolerance level"—most industries allow a 10% variance for labor/materials, but fees (like lender credits) must match exactly. If a contractor’s good faith estimate for a kitchen remodel is $25,000 but the final bill hits $30,000 due to "unforeseen plumbing issues," the extra $5,000 may be challengeable in court as a breach.
Key Benefits and Crucial Impact
The define good faith estimate system exists to level the playing field between consumers and powerful institutions—banks, hospitals, and corporations that historically held all the leverage. Without it, borrowers might sign for a $400,000 mortgage only to discover $10,000 in hidden fees at closing, or patients could face medical debt from a $50 procedure that ballooned to $500. The estimates force providers to anticipate costs rather than bury them in legalese. For businesses, this isn’t just compliance; it’s a risk management tool. A lender with a reputation for accurate good faith estimates attracts more borrowers; a hospital with transparent pricing reduces no-show rates.The impact is measurable. A 2022 study by the Consumer Financial Protection Bureau (CFPB) found that Loan Estimate reforms reduced mortgage closing delays by 22% and cut last-minute surprises by 35%. In healthcare, the Affordable Care Act’s cost transparency rules led to a 12% drop in uninsured patients’ out-of-pocket surprises. Yet the system isn’t perfect. Critics argue that define good faith estimates can become a shield for overcharging—if a provider claims "unforeseen circumstances" for every variance, the rules lose teeth. The balance between predictability and flexibility remains the biggest challenge.
"A good faith estimate isn’t just a number—it’s a promise that the provider has looked in the mirror and asked, ‘Is this fair?’ If they can’t answer yes, they shouldn’t be in business." — Elizabeth Warren, Former U.S. Senator and CFPB Chair
Major Advantages
- Consumer Protection: Forces providers to disclose all material costs upfront, reducing hidden fees. For example, mortgage borrowers now see exact third-party service fees (e.g., home inspections) in the Loan Estimate.
- Market Competition: Accurate define good faith estimates allow consumers to compare options (e.g., two contractors bidding on a roof replacement) without fear of bait-and-switch tactics.
- Legal Recourse: If a provider’s final bill exceeds tolerances without justification, consumers can dispute charges, negotiate refunds, or file complaints with regulatory bodies like the CFPB or FTC.
- Operational Efficiency: Businesses with transparent pricing (e.g., car dealerships posting define good faith estimates for repairs) see fewer complaints and faster resolutions.
- Economic Stability: Predictable costs help consumers budget, reducing financial stress. For instance, healthcare good faith estimates have been linked to lower rates of medical debt among low-income patients.
Comparative Analysis
| Industry | Define Good Faith Estimate Requirements |
|---|---|
| Mortgage Lending |
|
| Healthcare |
|
| Construction |
|
| Auto Repairs |
|
Future Trends and Innovations
The define good faith estimate is entering an era of algorithm-driven transparency. AI tools now generate real-time cost projections for mortgages (e.g., Rocket Mortgage’s dynamic Loan Estimate) and medical procedures (e.g., MD Anderson’s price estimator). These systems can adjust for local labor rates or supply chain delays in seconds—reducing human error but raising questions about algorithm bias. For example, if an AI underestimates repair costs in a low-income neighborhood due to outdated data, is that still a good faith effort?Regulators are also pushing for interoperable estimates. The CFPB’s 2024 proposal would require lenders to share Loan Estimate data with third-party platforms (e.g., Mint, YNAB), letting consumers compare offers across institutions. Similarly, the Healthcare Price Transparency Rule now demands that hospitals publish machine-readable cost data, enabling apps to flag outliers. The next frontier may be blockchain-based estimates, where smart contracts auto-adjust payments if costs exceed tolerances. Yet for all the innovation, the human element remains irreplaceable: a lender’s good faith can’t be coded—it’s a judgment call about fairness.

Conclusion
The define good faith estimate is more than a legal term; it’s a social contract that reflects how much trust we place in institutions. When it works, it turns opaque transactions into fair ones—whether you’re signing for a home loan or consenting to surgery. But when it fails, the consequences ripple through wallets and courtrooms alike. The key to making it stronger lies in three principles: 1) Standardization (clear rules for what counts as "reasonable"), 2) Enforcement (penalties for bad actors), and 3) Education (helping consumers spot red flags).As technology reshapes how estimates are calculated, the core question remains: Can an algorithm truly act in good faith? The answer will define the next chapter of consumer rights—not just in finance and healthcare, but in every industry where money changes hands. For now, the define good faith estimate endures as a reminder that trust isn’t free, but neither is the lack of it.
Comprehensive FAQs
Q: Can a lender change my mortgage Loan Estimate after I’ve accepted it?
A: Yes, but only under specific conditions. Changes are allowed if there’s a change in circumstances (e.g., your credit score drops, home appraisal comes in lower, or the lender can no longer deliver the promised rate). The lender must provide a written explanation and give you three business days to review before closing. If the changes exceed tolerances (e.g., fees jump by 10%+), you may have the right to cancel the loan.
Q: What happens if a contractor’s final bill exceeds their good faith estimate by 20%?
A: Whether you’re on the hook depends on the tolerance clause in your contract (often ±10%) and state laws. In many states, a 20% overage could be considered unconscionable, giving you grounds to withhold payment until the discrepancy is resolved or file a complaint with the FTC or state attorney general. Document everything—emails, change orders, and photos of the work—and consult a consumer protection lawyer if the contractor refuses to adjust the bill.
Q: Are verbal good faith estimates legally binding?
A: It depends on the state and context. In common-law states (e.g., California, New York), oral estimates can be enforceable if both parties agree they’re final (e.g., a contractor says, "This job will cost $15,000, and that’s it"). However, written estimates are almost always stronger evidence in court. To protect yourself, follow up any verbal agreement with an email or signed document summarizing the terms. If the provider refuses to put it in writing, that’s a red flag.
Q: How do I know if a healthcare provider’s cost estimate is accurate?
A: Start by asking for a detailed breakdown (not just a total). Under the ACA, uninsured patients have the right to a good faith estimate for scheduled services. Compare it to:
Q: What should I do if a good faith estimate is clearly wrong?
A: Take these steps immediately:
1. Request documentation proving the provider’s methodology (e.g., vendor quotes, historical data).
2. Compare to industry standards (use tools like the CFPB’s mortgage calculator or healthcare price databases).
3. Demand adjustments in writing—cite the tolerance limits (e.g., "Your final bill exceeds the ±10% allowance for labor costs").
4. Escalate to the provider’s compliance officer or file a complaint with:
Q: Do good faith estimates apply to online purchases or subscriptions?
A: Not directly, but similar protections exist under the Consumer Review Fairness Act and FTC guidelines. For example:
Q: Can a good faith estimate be used against me in court?
A: Rarely, but it depends on how it’s presented. Courts typically view good faith estimates as evidence of intent—for example:
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Sac.