How to Apply for Medicare Card: Step-by-Step Essentials for 2024
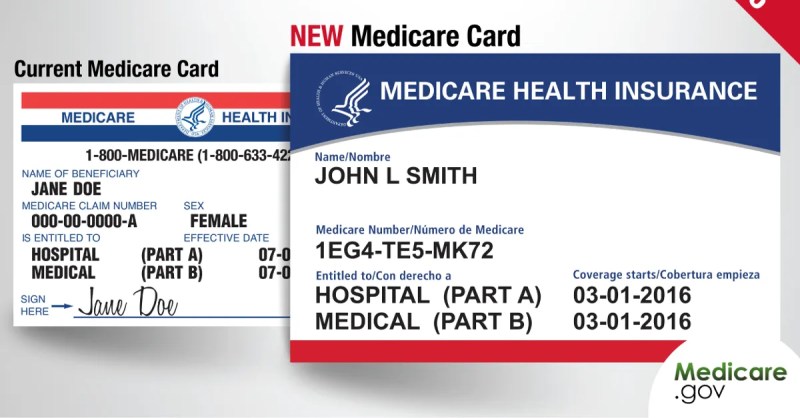
Medicare isn’t just another government program—it’s a lifeline for millions of Americans aged 65 and older, as well as younger individuals with disabilities or specific health conditions. Yet, despite its critical role, the process of how to apply for Medicare card remains shrouded in confusion for many. The stakes are high: missing enrollment deadlines can result in late penalties, while incorrect applications may delay access to essential healthcare services. Whether you’re approaching eligibility age or qualifying due to a disability, understanding the nuances of Medicare enrollment is non-negotiable.
The system itself is a patchwork of parts—A, B, C, and D—each serving distinct purposes, from hospital coverage to prescription drugs. But before diving into those details, the foundational step is securing your Medicare card. This plastic credential isn’t just a piece of plastic; it’s your gateway to doctors, hospitals, and the financial protections that come with it. The application process, however, isn’t one-size-fits-all. It varies based on whether you’re automatically enrolled, choosing to sign up manually, or navigating special circumstances like working past 65.
For those who’ve spent decades contributing to Social Security, the transition to Medicare can feel abrupt. The key to a smooth transition lies in preparation—knowing when to apply, where to submit documents, and how to avoid common pitfalls. This guide cuts through the bureaucratic jargon to provide a clear, actionable roadmap for how to apply for Medicare card, ensuring you’re equipped to make informed decisions about your healthcare future.
The Complete Overview of How to Apply for Medicare Card
Medicare’s enrollment process is designed to be accessible, but its complexity often leaves applicants overwhelmed. At its core, how to apply for Medicare card hinges on three primary pathways: automatic enrollment, manual application via Social Security, or online through the Medicare.gov portal. Each method has its own set of requirements, deadlines, and potential pitfalls. For instance, individuals who begin receiving Social Security benefits before turning 65 are automatically enrolled in Medicare Parts A and B, eliminating the need for proactive action—though verifying receipt of the card is still advisable. Meanwhile, those who delay retirement or lack Social Security credits must take initiative, risking enrollment gaps that trigger financial penalties.The timeline for applying for Medicare card is equally critical. The Initial Enrollment Period (IEP) spans seven months, starting three months before your 65th birthday and ending three months after. Missing this window forces applicants into the General Enrollment Period (GEP), which runs from January 1 to March 31 each year, but comes with a 10% premium increase for Part B coverage. Special Enrollment Periods (SEPs) exist for specific scenarios—such as late retirees with employer coverage—but navigating these exceptions requires precise documentation and timing. Understanding these periods is the first step in avoiding costly mistakes during the application process.
Historical Background and Evolution
Medicare’s origins trace back to the 1965 amendments to the Social Security Act, signed into law by President Lyndon B. Johnson. The program was born out of necessity: a growing elderly population with limited access to affordable healthcare, coupled with the political momentum of the Great Society era. Initially, Medicare covered hospital insurance (Part A) and medical insurance (Part B), reflecting the bipartisan consensus that healthcare was a fundamental right, not a privilege. Over the decades, however, the program expanded to include prescription drug coverage (Part D) and private plan options (Part C), adapting to the evolving needs of beneficiaries and the shifting healthcare landscape.The evolution of how to apply for Medicare card mirrors broader technological and administrative changes. In its early years, enrollment was a cumbersome, paper-based affair, requiring in-person visits to Social Security offices. The digital revolution transformed this process: today, applicants can initiate enrollment online, receive instant confirmation, and even manage their benefits via mobile apps. Yet, despite these advancements, the core principles remain unchanged—eligibility is tied to age, disability, or end-stage renal disease, and the application process must align with federal deadlines. Understanding this history contextualizes why the system operates the way it does, from the automatic enrollment for retirees to the manual processes for those who opt out of Social Security.
Core Mechanisms: How It Works
The mechanics of applying for Medicare card are rooted in a combination of automatic triggers and proactive actions. For most Americans, eligibility kicks in at 65, provided they’ve paid Medicare taxes for at least 10 years (40 quarters). Those who qualify automatically receive their Medicare card in the mail three months before their birthday, along with a welcome packet outlining their benefits. However, if you’re still working past 65—especially if your employer offers health coverage—you may choose to delay Part B enrollment to avoid unnecessary premiums. In such cases, how to apply for Medicare card becomes a deliberate choice, tied to your employment status and healthcare needs.Table of Contents
- The Complete Overview of How to Apply for Medicare Card
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: Can I apply for Medicare card online if I’m not yet 65?
- Q: What happens if I miss the Initial Enrollment Period?
- Q: Do I need to apply separately for Parts A, B, C, and D?
- Q: Can I keep my employer health insurance after 65?
- Q: What documents do I need to apply for Medicare card?
- Q: How long does it take to receive my Medicare card after applying?
- Q: Can I change my Medicare plan after enrollment?
- Q: What if I lose my Medicare card?
- Q: Are there any costs associated with Medicare?
- Q: Can I apply for Medicare if I’m not a U.S. citizen?
- Q: What’s the difference between Medicare and Medicaid?
For those who must apply manually, the process begins with gathering documentation: proof of citizenship, evidence of age (like a birth certificate), and records of employment or military service. The application can be submitted online, by phone, or in person at a Social Security office. Each method has its advantages—online applications offer convenience, while in-person visits provide immediate clarification for complex cases. Once submitted, processing typically takes 10–30 days, though expedited requests may be possible under certain conditions. The card itself arrives separately from the approval notice, and it’s essential to activate it by sharing it with healthcare providers to ensure coverage begins as expected.
Key Benefits and Crucial Impact
Medicare isn’t merely a safety net; it’s a cornerstone of financial security for millions. For seniors, it reduces the burden of exorbitant medical bills, while for disabled individuals, it provides a lifeline to critical care. The program’s impact extends beyond individual beneficiaries, influencing healthcare policy, provider networks, and even economic stability. Without Medicare, the cost of chronic illness or unexpected emergencies could push families into debt or force difficult trade-offs between healthcare and other necessities. The ability to apply for Medicare card on time is the first step in unlocking these protections, ensuring access to preventive care, specialist visits, and hospital services without the fear of prohibitive costs.The psychological and practical benefits of Medicare enrollment are equally significant. Knowing that a hospital stay won’t bankrupt you, or that a prescription drug won’t go unfilled, offers peace of mind. For caregivers, Medicare simplifies the process of managing healthcare for loved ones, reducing administrative stress. Yet, these benefits are only realized if the application process is navigated correctly. A delayed or denied Medicare card can create gaps in coverage, leaving beneficiaries vulnerable during their most critical health moments. This is why understanding how to apply for Medicare card—and doing so proactively—isn’t just a bureaucratic formality; it’s a strategic move toward long-term well-being.
"Medicare is more than a program; it’s a promise to America’s seniors and disabled citizens that they won’t face healthcare insecurity in their golden years." — Centers for Medicare & Medicaid Services (CMS) Official Statement, 2023
Major Advantages
- Financial Protection: Medicare covers a significant portion of hospital (Part A) and medical (Part B) expenses, including doctor visits, lab tests, and preventive services. Without it, out-of-pocket costs could reach tens of thousands per year.
- Access to Specialized Care: The program ensures access to specialists, rehabilitation services, and durable medical equipment (like wheelchairs or oxygen tanks) without prior authorization hassles.
- Prescription Drug Coverage (Part D): For those with chronic conditions, Medicare’s prescription drug plans cap monthly costs, making medications affordable. Enrolling during the IEP avoids late penalties.
- Portability: Medicare follows you nationwide, eliminating concerns about coverage gaps when traveling or relocating. This is particularly valuable for retirees who split time between states.
- Preventive Services at No Cost: Annual wellness visits, flu shots, and cancer screenings are fully covered under Parts A and B, promoting early intervention and better health outcomes.

Comparative Analysis
| Automatic Enrollment | Manual Application |
|---|---|
| Triggered by Social Security benefits; no action required. | Initiated online, by phone, or in person; requires documentation. |
| Card arrives 3 months before 65th birthday. | Processing takes 10–30 days; expedited requests may apply. |
| Covers Parts A and B by default. | Allows delayed enrollment (e.g., Part B if working past 65). |
| No late penalties if enrolled on time. | Missed deadlines incur 10% Part B premium increases. |
Future Trends and Innovations
The Medicare landscape is evolving, driven by demographic shifts, technological advancements, and policy reforms. By 2030, one in five Americans will be 65 or older, straining the system’s resources. In response, Medicare is exploring value-based care models, where payments are tied to health outcomes rather than service volume. This shift could simplify how to apply for Medicare card by integrating coverage with preventive care incentives, though it may also require beneficiaries to navigate new provider networks. Additionally, telehealth expansion—accelerated by the COVID-19 pandemic—is likely to become permanent, offering more flexible access to care and potentially streamlining administrative processes.Innovations in digital enrollment are another frontier. Biometric verification, AI-driven eligibility checks, and real-time benefit updates could reduce processing times for applying for Medicare card from weeks to days. However, these changes must balance efficiency with security, as fraud remains a persistent challenge. For applicants, staying informed about these trends is crucial, as they may introduce new enrollment options or alter existing deadlines. The future of Medicare isn’t just about coverage—it’s about adapting to a healthcare ecosystem that prioritizes accessibility, affordability, and innovation.

Conclusion
The process of how to apply for Medicare card is more than a bureaucratic hurdle; it’s the first step toward securing a stable healthcare foundation. Whether you’re automatically enrolled or choosing to act proactively, the key to success lies in understanding your eligibility, adhering to deadlines, and gathering the necessary documentation. Medicare’s structure may seem complex, but breaking it down into manageable steps—from Parts A and B to supplemental plans—makes the journey clearer. The stakes are high, but the rewards—financial security, access to care, and peace of mind—are invaluable.For those approaching eligibility, the time to act is now. Delaying the application can lead to unnecessary penalties and coverage gaps, while proactive planning ensures a seamless transition into Medicare. By leveraging the resources provided by Social Security and Medicare.gov, applicants can navigate the process with confidence. In an era where healthcare costs continue to rise, Medicare remains one of the most reliable safeguards against financial vulnerability. Mastering how to apply for Medicare card isn’t just about paperwork—it’s about safeguarding your health and future.
Comprehensive FAQs
Q: Can I apply for Medicare card online if I’m not yet 65?
A: No. Medicare enrollment is tied to age 65 (or disability/ESRD qualification). You can prepare by creating a MySocialSecurity account to streamline the process once eligible, but applications are only accepted during your Initial Enrollment Period (IEP).
Q: What happens if I miss the Initial Enrollment Period?
A: Missing your IEP forces you into the General Enrollment Period (January–March), which triggers a 10% Part B premium increase for every 12-month period you were eligible but didn’t enroll. You can still apply, but costs rise significantly.
Q: Do I need to apply separately for Parts A, B, C, and D?
A: Part A is automatic if you’ve paid Medicare taxes for 10+ years. Part B requires a separate enrollment action (unless you’re automatically enrolled). Parts C (Medicare Advantage) and D (prescription drugs) are voluntary and must be chosen during open enrollment periods.
Q: Can I keep my employer health insurance after 65?
A: Yes, but if your employer has 20+ employees, you can delay Part B without penalty. For smaller employers, you must enroll in Part B at 65 to avoid gaps. Always check COBRA rules if leaving a job.
Q: What documents do I need to apply for Medicare card?
A: Proof of age (birth certificate, passport), U.S. citizenship/residency (green card, naturalization papers), and employment records (W-2s, tax filings). If applying due to disability, provide SSA disability approval documents.
Q: How long does it take to receive my Medicare card after applying?
A: Processing takes 10–30 days, but your card may arrive separately. If you don’t receive it within 30 days, contact Social Security at 1-800-772-1213. Temporary coverage starts once your application is approved.
Q: Can I change my Medicare plan after enrollment?
A: Yes, during the Annual Enrollment Period (October 15–December 7) or if you qualify for a Special Enrollment Period (e.g., moving out of your plan’s service area). Outside these windows, changes are limited unless you have a life event.
Q: What if I lose my Medicare card?
A: Request a replacement online via MyMedicare.gov or by calling 1-800-MEDICARE (1-800-633-4227). You’ll need your Social Security number and other personal details for verification. Always keep a digital copy as a backup.
Q: Are there any costs associated with Medicare?
A: Part A is premium-free for most enrollees, but Parts B, C, and D have monthly costs (premiums). Deductibles and copays apply for services. Low-income individuals may qualify for Extra Help or Medicaid to reduce expenses.
Q: Can I apply for Medicare if I’m not a U.S. citizen?
A: Permanent legal residents (green card holders) who’ve lived in the U.S. for 5+ years are eligible. Temporary visitors or undocumented immigrants do not qualify for Medicare.
Q: What’s the difference between Medicare and Medicaid?
A: Medicare is a federal program for seniors/disabled individuals, while Medicaid is a joint federal-state program for low-income individuals. Some beneficiaries qualify for both (dual eligibility) and can use Medicaid to cover Medicare premiums or out-of-pocket costs.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Sac.