Unveiling the Mystery: What is a Roth Account?
In the realm of personal finance, understanding the nuances of investment vehicles is paramount. Among these, the Roth account stands out as a powerful tool for long-term savings and growth. This article delves deep into the question "what is a Roth account?", tracing its history, exploring its core mechanisms, and highlighting its key benefits.
Whether you're a seasoned investor or just starting to navigate the financial landscape, grasping the concept of Roth accounts can significantly enhance your strategic financial planning. By the end of this comprehensive overview, you'll have a clear understanding of how Roth accounts work and why they are a popular choice for those aiming to build a secure financial future.
Moreover, we'll compare Roth accounts with other investment options, analyze their future trends, and conclude with a thorough FAQ section to address any lingering questions. Let's embark on this financial journey, unraveling the mystery behind Roth accounts.
The Complete Overview of Roth Accounts
A Roth account, often referred to as a Roth IRA (Individual Retirement Account) or Roth 401(k), is a type of investment account that offers tax advantages for long-term savings. Unlike traditional accounts where contributions may be tax-deductible, the primary distinction of a Roth account is that contributions are made with after-tax dollars. This seemingly subtle difference has significant implications for how these accounts grow and are utilized over time.
The core appeal of Roth accounts lies in their ability to provide tax-free growth and withdrawals under certain conditions. This means that any earnings accrued within the account are not subject to capital gains taxes, and qualified withdrawals are entirely tax-free. This feature makes Roth accounts particularly attractive for those expecting to be in a higher tax bracket in retirement than during their working years.
Historical Background and Evolution
The inception of Roth accounts can be traced back to the Taxpayer Relief Act of 1997, which introduced the Roth IRA. This innovative account type was designed to offer an alternative to traditional IRAs, catering to individuals who wanted to benefit from tax-free growth and withdrawals. The Roth 401(k), a similar concept applied to employer-sponsored retirement plans, followed suit, further expanding the accessibility of these tax-advantaged accounts.
Table of Contents
- The Complete Overview of Roth Accounts
- Historical Background and Evolution
- Core Mechanisms: How Roth Accounts Work
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: What are the contribution limits for a Roth account?
- Q: Can I convert a traditional IRA to a Roth IRA?
- Q: What are the requirements for making a qualified withdrawal from a Roth account?
- Q: Are there any income limits for contributing to a Roth account?
- Q: Can I have both a Roth account and a traditional retirement account?
Over the years, Roth accounts have evolved to become a cornerstone of retirement planning and savings strategies. Legislative changes have refined their rules and expanded their eligibility, making them a versatile tool for various financial situations. The growing popularity of Roth accounts reflects a shift in financial planning, with more individuals recognizing the benefits of tax-free growth and the potential for a more secure retirement.
Core Mechanisms: How Roth Accounts Work
Understanding the mechanics of Roth accounts is crucial for maximizing their benefits. When you contribute to a Roth account, the funds are invested in various assets such as stocks, bonds, or mutual funds. Unlike traditional accounts, these contributions do not reduce your taxable income in the year they are made. However, the trade-off is that you can withdraw your contributions (but not earnings) at any time without tax implications or penalties.
The real value of a Roth account lies in the tax-free growth of earnings. As your investments within the account appreciate over time, the gains are not subject to capital gains taxes. This means that when you withdraw funds after reaching the age of 59½ and fulfilling other requirements, you pay no taxes on the earnings. This feature makes Roth accounts an efficient way to accumulate wealth for retirement or other long-term financial goals.
Key Benefits and Crucial Impact
Roth accounts offer a multitude of benefits that can significantly impact your financial well-being. By understanding these advantages, you can make informed decisions about incorporating Roth accounts into your investment strategy.
"The power of tax-free growth in a Roth account can substantially boost your retirement savings and provide a valuable safety net for future financial needs."
Major Advantages
- Tax-Free Withdrawals: Qualified withdrawals from a Roth account are entirely tax-free, allowing you to access your earnings without incurring additional tax liabilities.
- Tax-Free Growth: Earnings within the account grow tax-free, compounding over time to potentially yield substantial returns.
- Flexibility: While intended for retirement savings, Roth accounts offer flexibility, allowing for penalty-free withdrawals of contributions at any time.
- No Required Minimum Distributions: Unlike traditional IRAs, Roth accounts do not require you to start taking distributions at a specific age, providing more control over your savings.
- Potential Estate Planning Tool: Roth accounts can be a valuable part of your estate plan, as they can continue to grow tax-free for beneficiaries after your passing.

Comparative Analysis
| Feature | Roth Account | Traditional Account |
|---|---|---|
| Taxation of Contributions | After-tax | Pre-tax |
| Taxation of Earnings | Tax-free growth | Taxed upon withdrawal |
| Withdrawal Flexibility | Penalty-free withdrawal of contributions at any time | Early withdrawals may incur penalties |
| Required Minimum Distributions | No RMDs | RMDs start at age 72 |
Future Trends and Innovations
As financial landscapes continue to evolve, so too will the role of Roth accounts. Several trends and innovations are poised to shape the future of these investment vehicles:
Increasing awareness of the benefits of Roth accounts is likely to drive their popularity among younger investors. As millennials and Gen Z become more financially literate and focused on long-term savings, Roth accounts will appeal to their desire for flexibility and tax efficiency. Moreover, technological advancements in financial services will make accessing and managing Roth accounts more convenient, further enhancing their attractiveness.
Additionally, legislative changes may introduce new features or expand contribution limits, making Roth accounts even more powerful tools for retirement savings. The ongoing shift towards personalized financial advice and robo-advisors could also democratize access to Roth accounts, helping more individuals benefit from their advantages.

Conclusion
Understanding "what is a Roth account" is just the first step in harnessing the power of these remarkable financial tools. From their historical evolution to their core mechanics and significant benefits, Roth accounts offer a compelling strategy for long-term savings and growth.
By recognizing the advantages of tax-free growth and withdrawals, investors can make informed decisions to optimize their financial plans. As the future of personal finance unfolds, Roth accounts are poised to remain a cornerstone for those seeking to build a secure and prosperous future.
Comprehensive FAQs
Q: What are the contribution limits for a Roth account?
A: The contribution limits for Roth IRAs are set annually by the IRS. For 2023, the limit is $6,000 ($7,000 if you are age 50 or older) with a phase-out range for single filers between $129,000 and $144,000 of modified adjusted gross income (MAGI), and for married couples filing jointly between $207,000 and $217,000 of MAGI.
Q: Can I convert a traditional IRA to a Roth IRA?
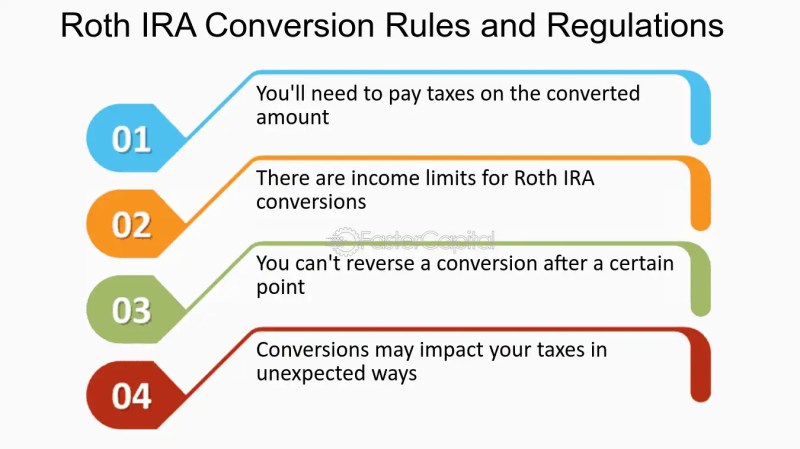
A: Yes, you can convert a traditional IRA to a Roth IRA, but it will be subject to taxation on the amount converted. The tax implications and eligibility rules for conversions vary, so it's advisable to consult with a financial advisor.
Q: What are the requirements for making a qualified withdrawal from a Roth account?
A: To make a qualified withdrawal from a Roth account without taxes or penalties, you must be at least 59½ years old, and the account must have been open for at least five years. Withdrawals before this period may incur taxes and penalties on the earnings.
Q: Are there any income limits for contributing to a Roth account?
A: Yes, there are income limits for contributing to a Roth IRA. The limits vary based on your filing status. For 2023, single filers with MAGI above $144,000 and married couples filing jointly with MAGI above $217,000 are not eligible to contribute directly to a Roth IRA, but they may be eligible for a "backdoor Roth IRA" contribution through a series of transactions.
Q: Can I have both a Roth account and a traditional retirement account?
A: Yes, you can have both a Roth account and a traditional retirement account, such as a traditional IRA or 401(k). Each type of account offers different tax advantages, so diversifying your retirement savings across both can be a strategic approach to optimizing your financial future.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Sac.