How to Attract High-Value Clients and Grow Your Tax Practice

Tax season isn’t just about filing returns—it’s a high-stakes opportunity to get more tax clients who value expertise, trust, and tangible results. The difference between a stagnant practice and a thriving one often lies in how deliberately a tax professional positions themselves. Passive waiting for referrals or hoping for walk-ins rarely yields high-value clients. Instead, success demands a mix of precision in service delivery, strategic outreach, and an understanding of what modern clients—especially affluent individuals and businesses—actually seek.
The numbers don’t lie: tax professionals who actively build their tax client base through targeted methods see 30–50% higher revenue growth annually. Yet many overlook the fact that client acquisition isn’t just about cold outreach—it’s about creating a system where clients choose you over competitors. This requires mastering both the art of client attraction and the science of retention, where every interaction reinforces your authority and reliability.
The Complete Overview of Growing a Tax Client Base
The foundation of getting more tax clients lies in recognizing that tax services are no longer a commodity. Clients today demand more than compliance—they want strategic financial guidance, risk mitigation, and personalized solutions. This shift means tax professionals must evolve from transactional advisors to trusted partners, blending technical expertise with business acumen.At its core, expanding your tax client roster hinges on three pillars: visibility (being found by the right audience), credibility (proving expertise through thought leadership), and accessibility (making engagement seamless). Each pillar requires a tailored approach—whether through digital marketing, networking, or niche specialization. The most effective strategies combine offline authority-building with online lead generation, ensuring a steady pipeline of qualified prospects.
Historical Background and Evolution
Tax advisory as a profession has undergone dramatic transformations, especially in the last two decades. Historically, tax practitioners relied on word-of-mouth referrals and local business networks to grow their tax client list. The rise of personal computers and accounting software in the 1990s democratized basic tax prep, but it also created competition. Clients who once had no alternative now had options—including DIY solutions and online tax filers.The turning point came with the digital revolution. By the mid-2000s, tax professionals who embraced online visibility—through websites, email marketing, and early social media—began attracting more tax clients than their offline-only counterparts. Today, the landscape is even more competitive, with AI-driven tools and regulatory changes forcing practitioners to specialize. Those who focus on acquiring tax clients strategically—by targeting niches like real estate investors, high-net-worth individuals, or tech startups—now dominate the market.
Core Mechanisms: How It Works
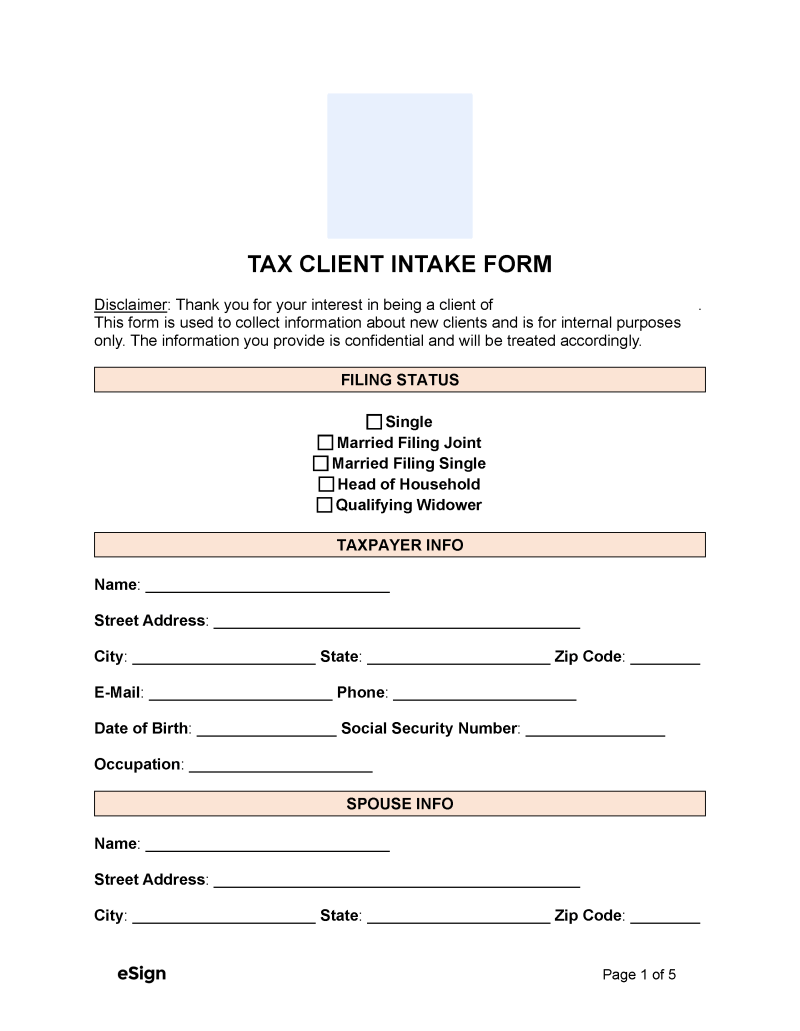
The mechanics of getting more tax clients revolve around two critical phases: attraction and conversion. Attraction is about positioning yourself as the go-to expert in a specific area—whether it’s international tax planning, S corporation filings, or estate tax strategies. This requires content that educates, such as blog posts, webinars, or case studies demonstrating your unique value.Conversion, meanwhile, depends on a frictionless client journey. A potential client might first encounter your LinkedIn post on tax-saving tips, then download a free guide from your website, and finally book a consultation after seeing testimonials from similar clients. Each step is designed to reduce hesitation and build trust. The most successful tax professionals systematize this process, using CRM tools to track leads and follow-ups, ensuring no opportunity slips through the cracks.
Key Benefits and Crucial Impact
The rewards of expanding your tax client base extend beyond revenue. A robust client list provides financial stability, allowing practitioners to invest in better tools, hire support staff, or even transition into advisory roles. More clients also mean more referrals, creating a self-sustaining growth loop. However, the real advantage lies in specialization—when you focus on acquiring tax clients in a niche, you command premium rates and become indispensable to your target market.Table of Contents
- The Complete Overview of Growing a Tax Client Base
- Historical Background and Evolution
- Core Mechanisms: How It Works
- Key Benefits and Crucial Impact
- Major Advantages
- Comparative Analysis
- Future Trends and Innovations
- Conclusion
- Comprehensive FAQs
- Q: How quickly can I expect to see results from implementing these strategies?
- Q: Should I focus on individual taxpayers or businesses to get more tax clients?
- Q: What’s the best way to stand out in a crowded market?
- Q: How important is networking in getting more tax clients?
- Q: Can I really charge higher fees by specializing?
- Q: What’s the biggest mistake tax professionals make when trying to get more tax clients?
Beyond the financial upside, a growing practice offers intangible benefits: greater influence in professional circles, opportunities for speaking engagements, and the ability to shape industry standards. Clients themselves become ambassadors, singing your praises to peers who need similar expertise.
"The tax professional who stops learning stops earning." — Robert Kiyosaki (adapted)
Major Advantages
- Higher Revenue Streams: Specialized tax services command 20–40% higher fees than general filings, making getting more tax clients in niches far more lucrative.
- Reduced Seasonal Volatility: Diversified client bases smooth out cash flow fluctuations, ensuring steady income year-round.
- Enhanced Credibility: A full roster of satisfied clients acts as social proof, making it easier to attract new tax clients through referrals and reviews.
- Scalability Opportunities: A larger client base allows for delegation, outsourcing, or even franchising tax services to other professionals.
- Future-Proofing: Clients who see you as a strategic partner are less likely to switch to competitors, ensuring long-term retention.

Comparative Analysis
| Traditional Methods | Modern Strategies |
|---|---|
| Relying on referrals and local networking. | Leveraging digital marketing (SEO, LinkedIn, email campaigns) to get more tax clients proactively. |
| Generalized tax services for all clients. | Specializing in high-demand niches (e.g., crypto taxes, exit planning) to command premium rates. |
| Passive waiting for clients to come. | Outbound lead generation via webinars, direct mail, and partnerships with CPAs. |
| One-time filing relationships. | Building recurring revenue through retainer-based advisory services. |
Future Trends and Innovations
The next frontier in growing your tax client base will be shaped by technology and shifting client expectations. Artificial intelligence is already automating routine filings, but the human touch—strategic planning, risk management, and personalized advice—remains irreplaceable. Tax professionals who focus on acquiring tax clients through AI-assisted tools (e.g., chatbots for initial consultations) while maintaining high-touch service will thrive.Additionally, the rise of remote work and global economies means clients will seek tax advisors with international expertise. Those who position themselves as cross-border specialists—helping expats, digital nomads, or multinational businesses—will have a distinct edge. The key is to stay ahead of regulatory changes while leveraging innovation to streamline client acquisition.
Conclusion
Getting more tax clients isn’t about luck—it’s about strategy, consistency, and adaptability. The tax professionals who succeed in the coming years will be those who treat client acquisition as a science, not a guessing game. This means investing in the right tools, refining your messaging, and continuously proving your value beyond compliance.The best time to start was years ago. The second-best time is now.
Comprehensive FAQs
Q: How quickly can I expect to see results from implementing these strategies?
A: Results vary, but tax professionals who combine niche specialization with digital marketing typically see a 10–20% increase in inquiries within 3–6 months. Retention-based strategies (like retainers) may take longer but yield higher lifetime value per client.
Q: Should I focus on individual taxpayers or businesses to get more tax clients?
A: Both are viable, but businesses (especially S Corps, LLCs, and startups) often require more complex services, allowing you to charge premium rates. Individuals may be easier to acquire initially, but B2B clients tend to provide recurring revenue.
Q: What’s the best way to stand out in a crowded market?
A: Differentiation comes from specialization and thought leadership. For example, positioning yourself as "The Tax Strategist for Real Estate Investors" or "The Crypto Tax Expert for Traders" makes you instantly memorable. Pair this with case studies or free resources to attract high-intent clients.
Q: How important is networking in getting more tax clients?
A: Critical—but not in the traditional sense. Instead of generic networking events, focus on high-value connections: partnering with CPAs for overflow clients, joining industry-specific groups (e.g., REIA for real estate investors), or collaborating with financial planners for cross-referrals.
Q: Can I really charge higher fees by specializing?
A: Absolutely. Clients pay for expertise, not just time. For instance, a tax professional specializing in international tax planning can charge 2–3x more than a generalist because their niche requires deeper knowledge of treaties, compliance, and risk mitigation.
Q: What’s the biggest mistake tax professionals make when trying to get more tax clients?
A: Assuming that being "good at taxes" is enough. Many overlook the need for a strong online presence, clear messaging, and a system for follow-ups. Without these, even the most skilled tax advisor will struggle to convert leads into clients.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of Sac.